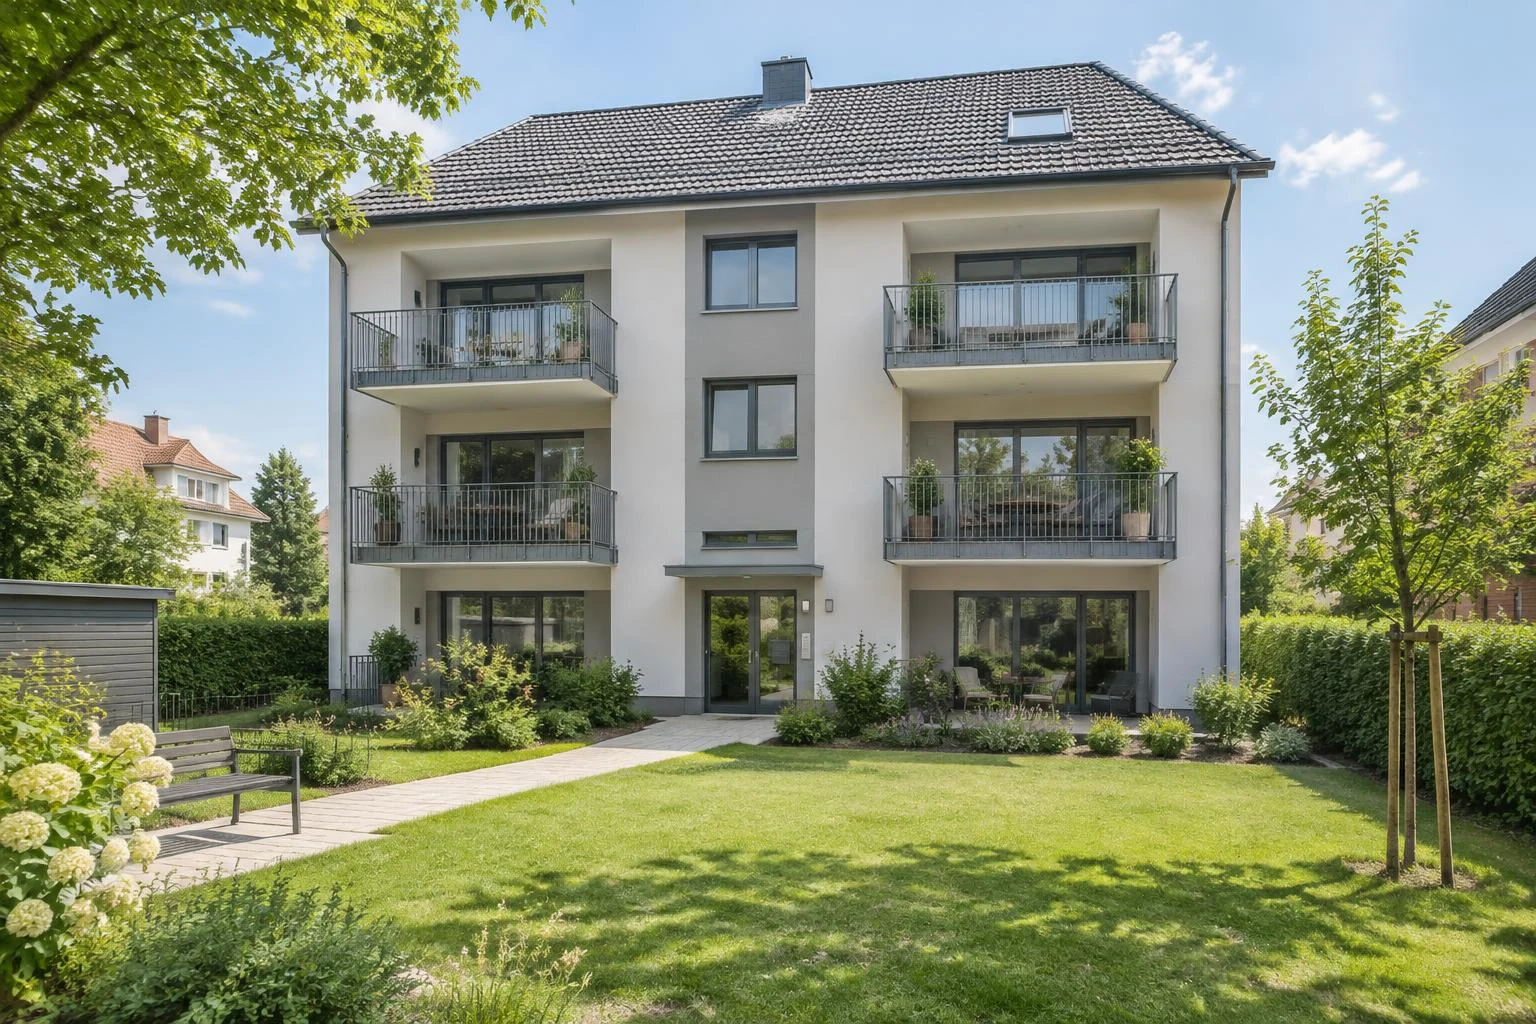
Apartment Building or Individual Apartments?
Comparing costs, cash flow and ownership responsibilities
 Eduard Winter
Investment Advisor at InvestImmo
01Apartment building or individual apartments: choosing your investment structure
Should you buy one rental building in Germany or spread your capital across individually owned apartments? Compare more than prices and rents. Management, borrowing, repairs and future sales all belong in the calculation. The right structure must fit both your resources and your tolerance for responsibility.
02Ownership, decisions and acquisition costs
An undivided building includes the property and land. German condominium ownership combines exclusive ownership of a unit with a co-ownership share in common property, governed by the Condominium Act, or WEG.
| Issue | Undivided building | Individual apartments |
|---|---|---|
| Building management | Your responsibility | Collective management |
| Repairs | Whole-building exposure | Allocated share |
| Organisation | One address | Potentially several associations |
| Selling | Initially the whole property | Individual units |
Agreements and resolutions govern collective management; voting requirements vary. Costs generally follow ownership shares, but alternative allocations are possible under sections 16 and 19 WEG.
Broker fees: Apartment buyers do not invariably pay no more than half. For consumer purchases, sections 656b–656d BGB address dual appointments and agreements passing broker costs to the other party. A buyer-only search mandate is different. These specific sharing provisions do not cover apartment buildings. Have the actual arrangement checked.

03Budgeting for management
Distinguish rental management from association management of common property and additional management of your individual tenancy. Compare services, VAT, minimum fees and extras. Valuation assumptions in Annex 3 ImmoWertV are not quotations for managing your property.
Management and maintenance are excluded from recoverable operating costs under section 1 BetrKV. Separate recoverable expenses, owner expenses and reserve contributions within the association charge, known as Hausgeld.
04Three options, one purchase budget
Every figure below is an illustrative assumption, not market data or a financing offer. Purchase price: €860,000; acquisition costs: 10.07%, or €86,602; borrowing: €688,000. Required equity is therefore €258,602, excluding an additional liquidity buffer.
Assume 3.8% annual interest and 1.5% initial principal repayment. Annual debt service is €688,000 × 5.3% = €36,464. The repayment schedule determines its actual interest and principal components.
- A: One building containing six apartments and 420 m².
- B: Six individually owned apartments totalling 420 m² at the same price per square metre.
- C: Five apartments at a 15% higher price per square metre. Total area is exactly 420 ÷ 1.15 m², displayed as 365.2174 m².
Further assumptions: monthly rent excluding operating charges of €9.50/m², annual maintenance provision of €14/m² and a rent-loss allowance of 2% of scheduled rent. Rental or individual-unit management costs €30 per unit monthly; additional association management costs €29. Both assumptions include any applicable VAT.
Annual budget before tax
| Item | A: building | B: six apartments | C: five apartments |
|---|---|---|---|
| Scheduled rent | €47,880.00 | €47,880.00 | €41,634.78 |
| Total management | −€2,160.00 | −€4,248.00 | −€3,540.00 |
| Maintenance provision | −€5,880.00 | −€5,880.00 | −€5,113.04 |
| Rent-loss allowance | −€957.60 | −€957.60 | −€832.70 |
| Interest and principal | −€36,464.00 | −€36,464.00 | −€36,464.00 |
| Available surplus | €2,418.40 | €330.40 | −€4,314.96 |
Calculations use unrounded intermediate values; monetary amounts are rounded to cents. Recoverable operating expenses are assumed to balance completely. Other owner expenses, special assessments, major upgrades and selling costs are excluded.
The difference between A and B is exactly €2,088 in additional association management. C provides less rental space but has lower management costs than B because it contains five units rather than six. Its annual shortfall relative to A is €6,733.36, rounded. Both area and unit count matter.

05Calculate tax separately
Taxable rental income depends on actual receipts, deductible expenses and depreciation—not the budget surplus. Rental-related interest can be deductible; principal repayment is not an equivalent expense. See section 9 EStG.
Building depreciation requires an appropriate tax basis and the conditions in section 7 EStG, not an arbitrary building allocation. Standard straight-line rates for residential buildings are generally 2% for completion in 1925–2022, 2.5% before that period and 3% afterwards.
Association maintenance-reserve contributions are not immediately deductible. Qualifying expenditure from the reserve is generally decisive, as confirmed in Federal Fiscal Court case IX R 19/24. A budgeted rent-loss allowance likewise creates no separate cash expense.
Calculate the tax effect using your circumstances. Possible relief is neither immediate cash nor a guarantee of positive cash flow.
06Financing, diversification and selling
Section 4 BelWertV generally emphasises income-based valuation in its covered-bond lending context, with exceptions for suitable condominium property. This does not establish an automatic interest-rate disadvantage for buildings. Compare actual lending values, equity requirements and offers.
For diversification, investigate different employment markets and building risks rather than simply different postcodes. One building concentrates exposure at one address but allows coordination without other unit owners. Tenancy law and public-law requirements still apply.
Shared repairs are not free: Assuming an €85,000 roof project and an applicable 5% allocation, your apartment's share would be €4,250 before existing reserves. Use the actual allocation rule, not an assumed equal split between apartments.
Individual units allow smaller sales. Do not assume a building can later be divided freely: section 250 BauGB enables local permission requirements. Conversion can also trigger tenant purchase rights and restrictions on termination under sections 577 and 577a BGB.
07Conclusion
Consider a whole building when direct responsibility, adequate reserves and a sound location assessment align. Consider individual apartments when diversification and gradual sales matter more. Neither approach should depend on hoped-for appreciation or tax refunds to remain affordable. The stronger purchase is the one whose obligations you can meet under adverse conditions.
FAQFrequently asked questions
Is an apartment building more profitable than individual apartments?
Not automatically. The model produces an annual pre-tax surplus of €2,418.40 for the building and €330.40 for six equally priced apartments. Here, the difference comes entirely from assumed additional association management costs. Actual properties can produce different results.
How much equity does the example require?
With an assumed €860,000 purchase price, €86,602 in acquisition costs and €688,000 of borrowing, the required equity is €258,602. An additional buffer for repairs and payment shortfalls is needed.
Which apartment management costs should investors distinguish?
Separate management of the association's common property from management of your individual tenancy. Check services, VAT, minimum fees and extras. The total association charge is not simply a management fee.
Are German association maintenance-reserve contributions immediately deductible?
No. Paying into the reserve does not itself create an immediate rental-expense deduction. The timing and nature of the association's actual expenditure are generally decisive.
Are repairs automatically cheaper for an individual apartment?
No. You pay the share allocated to your unit under the applicable rules. Building condition, project scope and existing reserves determine your exposure, and additional special assessments may be necessary.
Can an apartment building later be divided into individual units?
It may be possible, but should not be assumed. Before buying, investigate division requirements, local permission rules, tenant protections and the requirements of any financing bank.
08Further reading
Apartment investment · Concentration risk · Portfolio building · Association charges · Property management · Cash-flow calculator
09Sources
Official sources: WEG, BetrKV, ImmoWertV, BelWertV, BauGB and EStG linked above; the complete BGB, particularly sections 577, 577a and 656b–656d; and the linked Federal Fiscal Court judgment.
General information about German property, not individual legal, tax or investment advice.
Writes about Taxes, AfA (depreciation), Existing properties and Portfolio building.
Since 2020, Eduard has bought seven properties of his own and supported more than 150 clients. He writes about tax levers, property documents and portfolio building – with honest numbers instead of rosy projections.
This guide does not replace tax or legal advice. All figures are example calculations with disclosed assumptions.