Investing in a Small Owners’ Association
Evaluate management, voting rights and reserves before buying an apartment
 Kevin Celentano
Investment Advisor at InvestImmo
01Small owners’ associations: assess management and cash needs
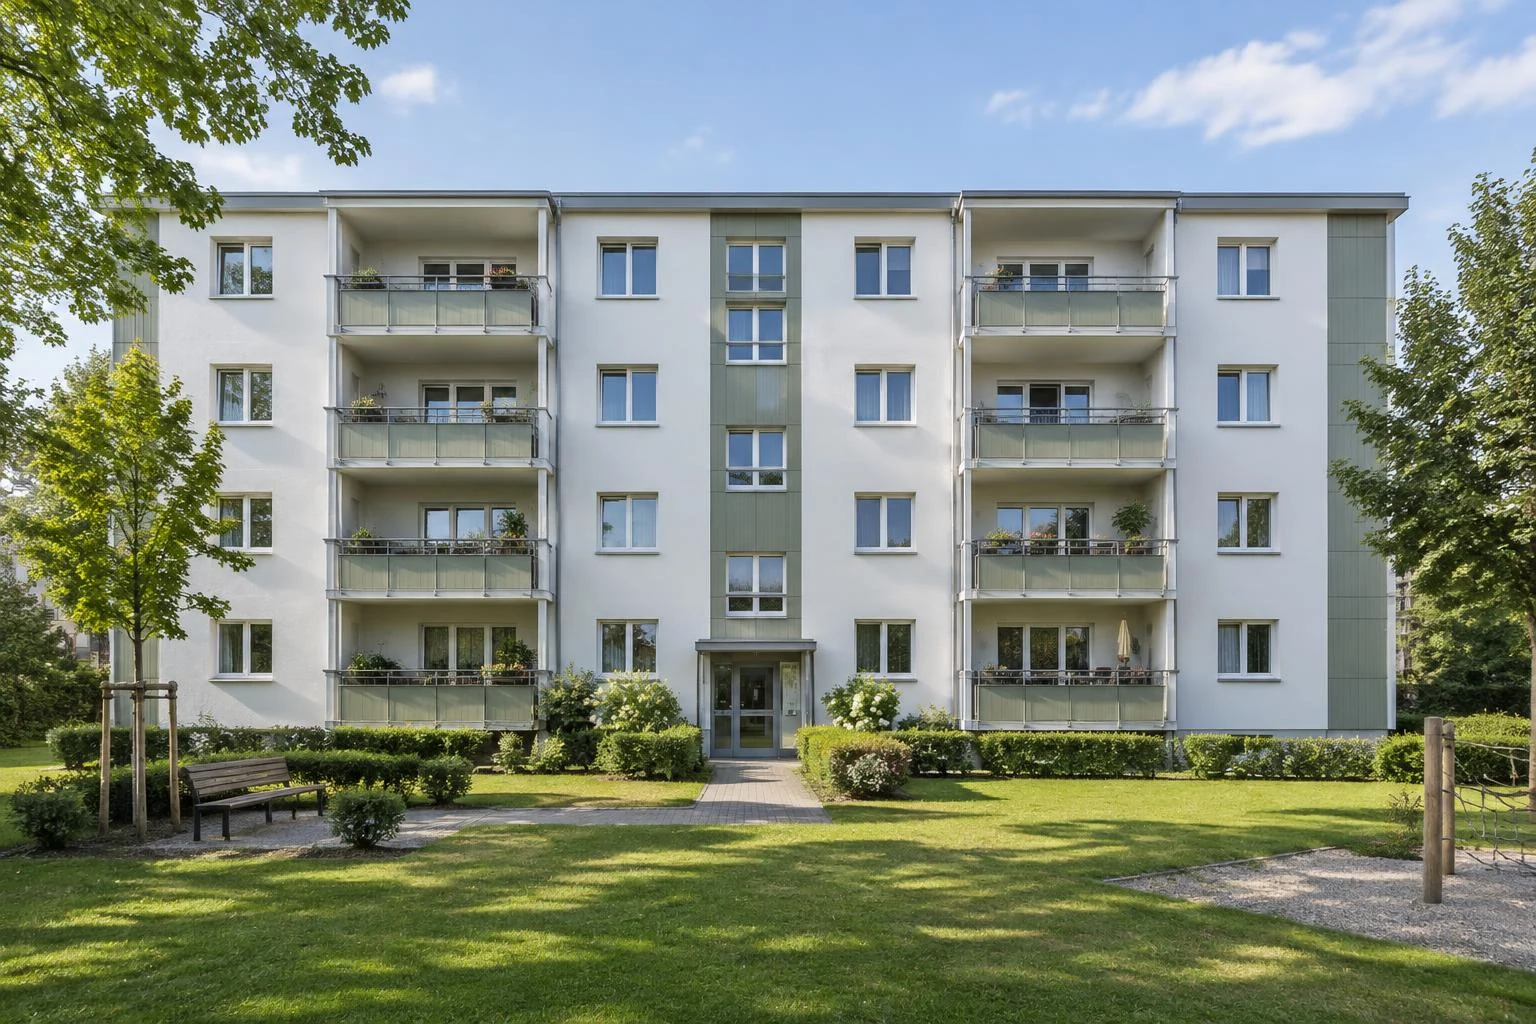
A well-kept four-apartment building, familiar neighbours and low monthly charges can look appealing. Before buying, ask whether those payments cover the building’s actual needs. Evaluate not just the apartment, but how its owners make decisions and finance shared responsibilities.
02Small building, ordinary legal framework
Here, “small” means two to eight apartments, not a separate legal category. Germany’s Condominium Act, or WEG, still applies. The declaration of division and community rules specify rights and arrangements; legally permissible departures from statutory defaults are possible. See section 10 WEG and our owners’ association guide.
Record the number of owners, voting rights and cost shares separately. Also check exclusive-use rights over gardens or parking spaces and their associated arrangements.

03What self-management actually means
The nine-unit threshold is not a general ban on self-management in larger associations. It concerns an exception to the entitlement to a certified manager. There must be fewer than nine separate ownership rights, an owner must be appointed manager, and fewer than one-third of owners must request certified management: section 19(2)(6) WEG.
Without an appointed manager, owners represent the association jointly. Check signing authority and powers of attorney rather than assuming any owner can independently instruct contractors or handle insurance matters: section 9b WEG.
Required records include the annual budget, annual accounts, asset report and register of resolutions. Establish who monitors payments, coordinates maintenance and handles insurance. Ask for accessible files and cover arrangements during absence: sections 24 and 28 WEG.
Landlords have a separate accounting deadline
The tenant must generally receive the operating-cost statement within twelve months after the accounting period ends. Later additional demands are normally excluded unless the landlord is not responsible for the delay: section 556(3) BGB.
A missing association resolution does not automatically extend that deadline. Request supporting records early and document your efforts. Association accounts also do not replace the correct allocation under the tenancy agreement: Federal Court of Justice, VIII ZR 249/15.
04Voting, deadlock and legal remedies
The statutory default is a majority of votes cast, with one vote per owner. Community rules may establish another permissible voting system. Two owners voting against each other create deadlock; under unit-based voting, ownership of three out of five apartments may instead confer a majority. Check voting exclusions and the particular decision: section 25 WEG.
A court may substitute a necessary resolution that owners fail to adopt. An action challenging a resolution generally must be filed within one month and substantiated within two months of its adoption. Do not wait for minutes: sections 44–45 WEG.
05Worked example: pre-tax cash flow
Every figure below is an assumption, not a market quotation or forecast. Purchase price: €220,000; loan: €176,000; equity towards the price: €44,000. Transfer tax, notary, land registration and any brokerage costs require additional funding and property-specific estimates.
Assume monthly rent excluding operating costs of €840, interest of 3.8% and initial principal repayment of 1.5%. This simplified model uses one year-end loan payment: €176,000 × 5.3% = €9,328. Monthly repayments would change the interest/principal split.
| Annual cash item | Self-managed | External manager |
|---|---|---|
| Rent excluding operating costs | €10,080 | €10,080 |
| Reserve contribution | −€600 | −€600 |
| Additional management fee | €0 | −€420 |
| Loan payment | −€9,328 | −€9,328 |
| Pre-tax cash flow | €152 | −€268 |
Monthly equivalents are €12.67 and −€22.33, rounded. The assumed management fee is €35 monthly; owners’ work is unpaid. Recoverable operating costs are assumed to balance completely. Vacancy, unpaid rent, other owner expenses and repairs inside the apartment are excluded: add your own contingency allowances. Management and repair expenses are not recoverable residential operating costs: section 1 BetrKV.
Keep tax separate
The year-end payment model produces €6,688 interest and €2,640 principal repayment. Rental-related interest may be deductible; principal repayment is not an equivalent expense. Depreciation also needs separate treatment and is not a recurring cash payment. See section 9 EStG.
Reserve contributions are not immediately deductible rental expenses. Tax treatment is assessed when the association actually spends the money, including whether the work qualifies for deduction: Federal Fiscal Court, IX R 19/24.
Obtain individual advice on the building allocation, depreciation basis, acquisition costs and repair treatment. An after-tax result would be unreliable without these details and your personal tax circumstances.

06Roof replacement: the special assessment
Further assumptions: roof costs of €48,000, available reserves of €16,000 and a 250/1,000 cost share, with no alternative allocation.
| Funding | Association | Your share |
|---|---|---|
| Roof costs | €48,000 | €12,000 |
| Reserve withdrawal | −€16,000 | −€4,000 |
| Special assessment | €32,000 | €8,000 |
Dividing €8,000 by annual fee savings of €420 gives approximately 19.05 years. This is a scale comparison, not proof that appointing a manager prevents roof costs. More apartments do not guarantee sufficient reserves either. Assess project scope, allocation and available funds together.
07Pre-purchase checklist
- [ ] Governing documents: Read the declaration, community rules, exclusive-use rights and cost allocations.
- [ ] Ownership: Map voting rights, multiple holdings and conflicting interests.
- [ ] Management: Check appointment, contract, remuneration and cover arrangements.
- [ ] Finances: Request three years of accounts, the budget, asset report, bank evidence and arrears information.
- [ ] Decisions: Review resolutions, minutes, litigation and proposed assessments.
- [ ] Building: Have the roof, façade, heating and pipework assessed; develop a ten-year maintenance outlook.
- [ ] Insurance: Review replacement-value building cover, property-owner liability, exclusions and deductibles. Appropriate insurance forms part of proper administration: section 19 WEG.
- [ ] Cooperation: Discuss responsibilities, payment discipline and repair decisions.
08Risks and conclusion
Treat deadlock, dominant owners, missing records, late accounts and unfunded work as investment risks. Positive indicators include transparent costs, clear responsibilities and documented decisions that are actually implemented. Self-management alone is neither a quality seal nor a reason to reject a property.
Proceed only with a credible overall calculation and sufficient personal liquidity. Low monthly charges deserve investigation; they do not prove investment quality.
FAQFrequently asked questions
What is a small owners’ association?
Here, the term describes a building with two to eight apartments, not a separate legal category. German WEG rules, community documents and the actual ownership structure determine how it operates.
Is self-management permitted only below nine units?
No. The threshold concerns an exception to the entitlement to certified management under section 19 WEG, not the general legality of self-management.
When does the exception to certified management cease to apply?
One trigger is a request for certified management from at least one-third of owners. With four distinct sole owners, two requesting it meet that threshold.
What happens when owners’ votes are tied?
A proposal without the required majority does not pass. Where a necessary decision is not adopted, an owner may seek a substitute court resolution under section 44 WEG.
Are maintenance reserve contributions immediately tax-deductible?
No. Under Federal Fiscal Court decision IX R 19/24, payment into the reserve alone does not create a rental-expense deduction. Actual expenditure and the tax classification of the work matter.
How much additional personal liquidity should I retain?
There is no reliable universal amount. Base your buffer on planned works, your allocated share, available association funds, potential rental shortfalls and additional owner expenses.
09Further reading
Certified managers · Monthly ownership charges · Common property costs · Reviewing meeting minutes · Extraordinary owners’ meetings
10Sources
- WEG, particularly sections 9b, 10, 19, 24, 25, 28, 44 and 45
- BGB, section 556 and BetrKV
- EStG, section 9; court decisions linked above. Sources are in German.
General information, not individual legal, tax or investment advice. Illustrative results are not guaranteed.
Writes about Purchase process, Notary and land registry and Letting.
Kevin combines twelve years of sales experience with nine years specialising in property and more than 500 consultations. He writes about property quality, location risks and a safe path from the first comparison to completion.
This guide does not replace tax or legal advice. All figures are example calculations with disclosed assumptions.